Answers/Solutions Only > 4.4,_4.7,_4.9,_4.12,_4.14,_4.20,_4.26 University of Illinois, Urbana Champaign IE 411
Related tags
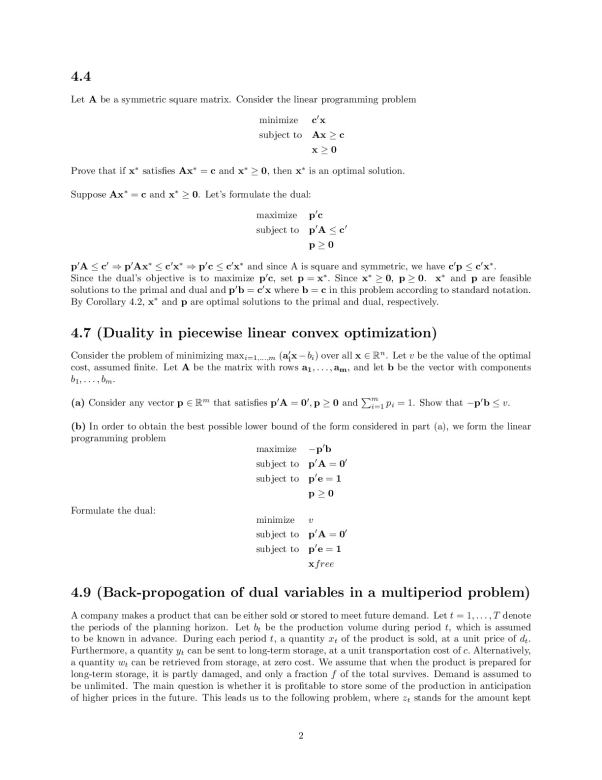
University of Illinois, Urbana ChampaignUniversity of Illinois, Urbana Champaign IE 411 4.4 Let A be a symmetric square matrix. Consider the linear programming problem minimize c 0x subject to Ax ≥ c x ≥ 0 Prove that if x ∗ satisfies Ax∗ = c and x ∗ ≥ 0, then x ∗ is an optimal solution. Suppose Ax∗ = c and x ∗ ≥ 0. Let’s formulate the dual: maximize p 0 c subject to p 0A ≤ c 0 p ...[Show More]
Similar Resources on Scholarfriends
Tip: shorter searches usually return better matches.
Searching Scholarfriends…
Access Full Document
Instant download
Preview 1 out of 4 pages
Reviews( 0 )
No Recommended Resources Yet.
| Category: | Answers/Solutions Only |
| Number of pages: | 4 |
| Language: | English |
| Last updated: | 2 years ago |
| Downloads: | 1 |
| Views: | 27 |
Need help with "4.4,_4.7,_4.9,_4.12,_4.14,_4.20,_4.26 University of Illinois, Urbana Champaign IE..."?
Get help from verified experts or start a custom project.


