QUIZ > Derivatitives q 4
Related tags
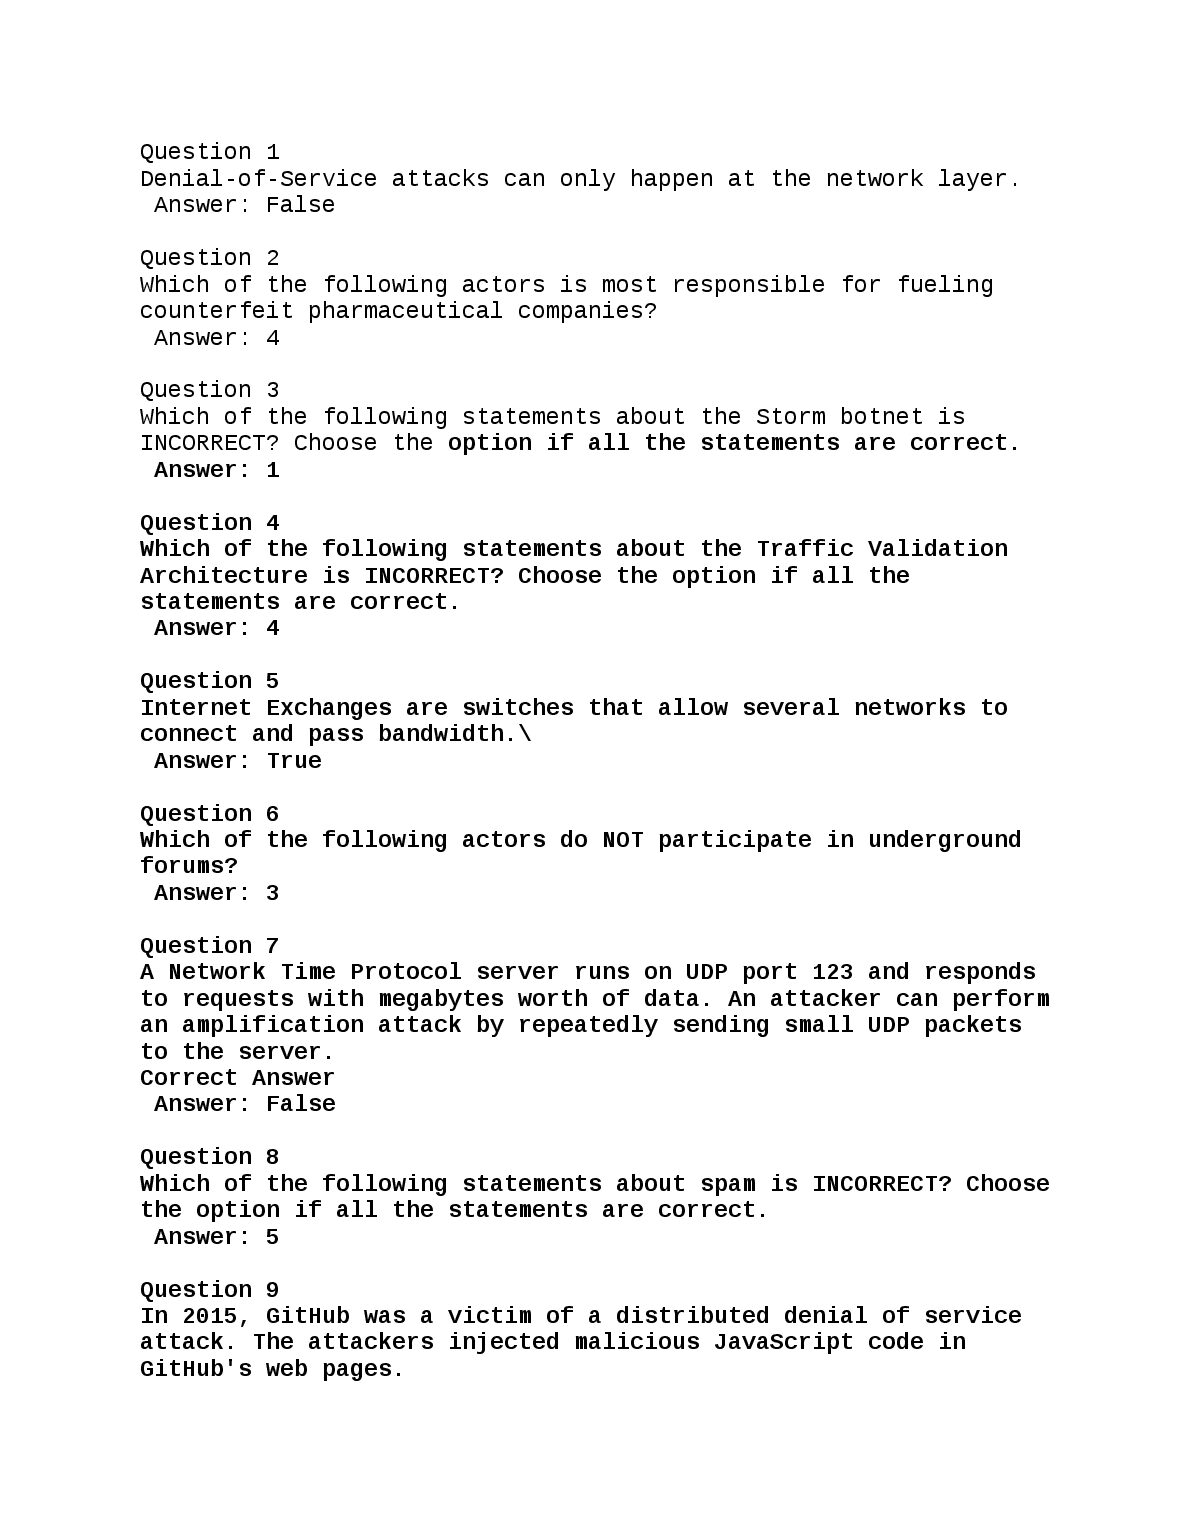
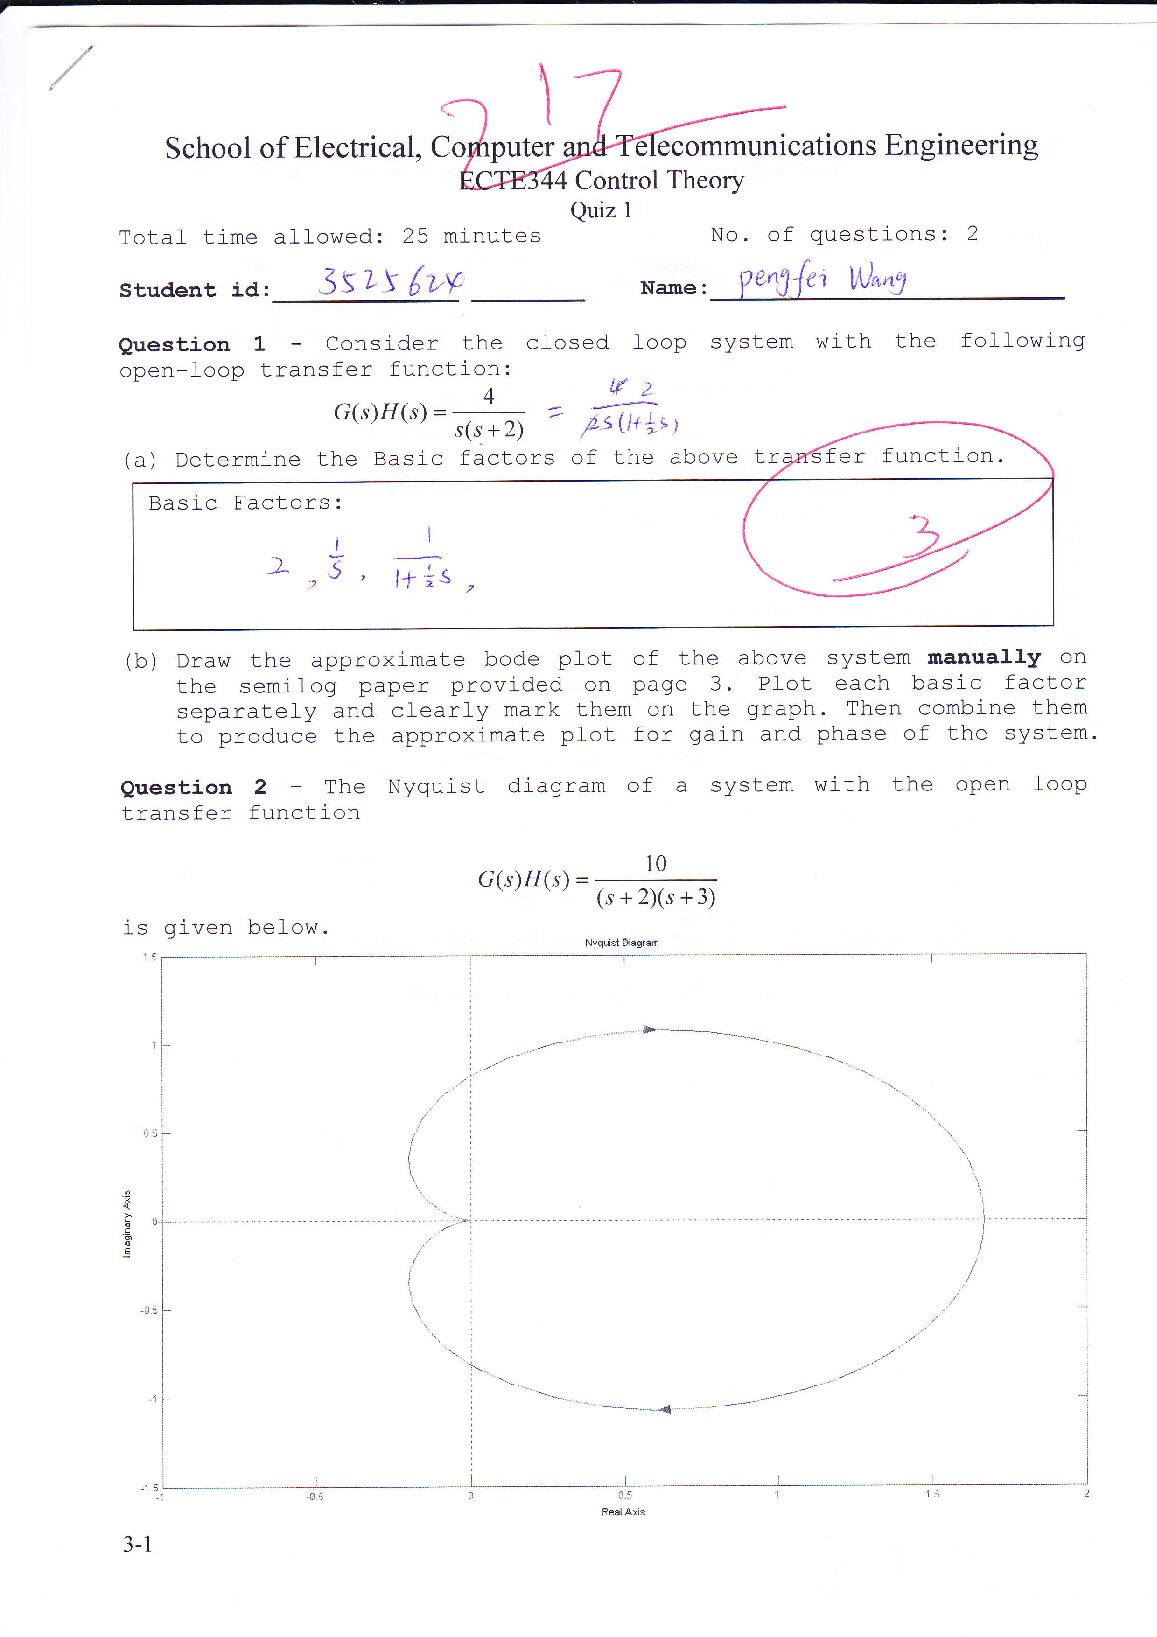
Western Sydney UniversityWestern Sydney University DERIVATIVE 200079 4. Using the Black-Scholes-Merton option pricing method, determine the following given the conditions described. The strike price is $34 over a stock currently trading at $37.55. which has a standard deviation of 42.22%pa. The time to expiry or the option is 341 days. The stock has announced that it shall ...[Show More]
Access Full Document
Instant download
Preview 1 out of 2 pages
Reviews( 0 )
No Recommended Resources Yet.
| Category: | QUIZ |
| Number of pages: | 2 |
| Language: | English |
| Last updated: | 2 years ago |
| Downloads: | 3 |
| Views: | 27 |