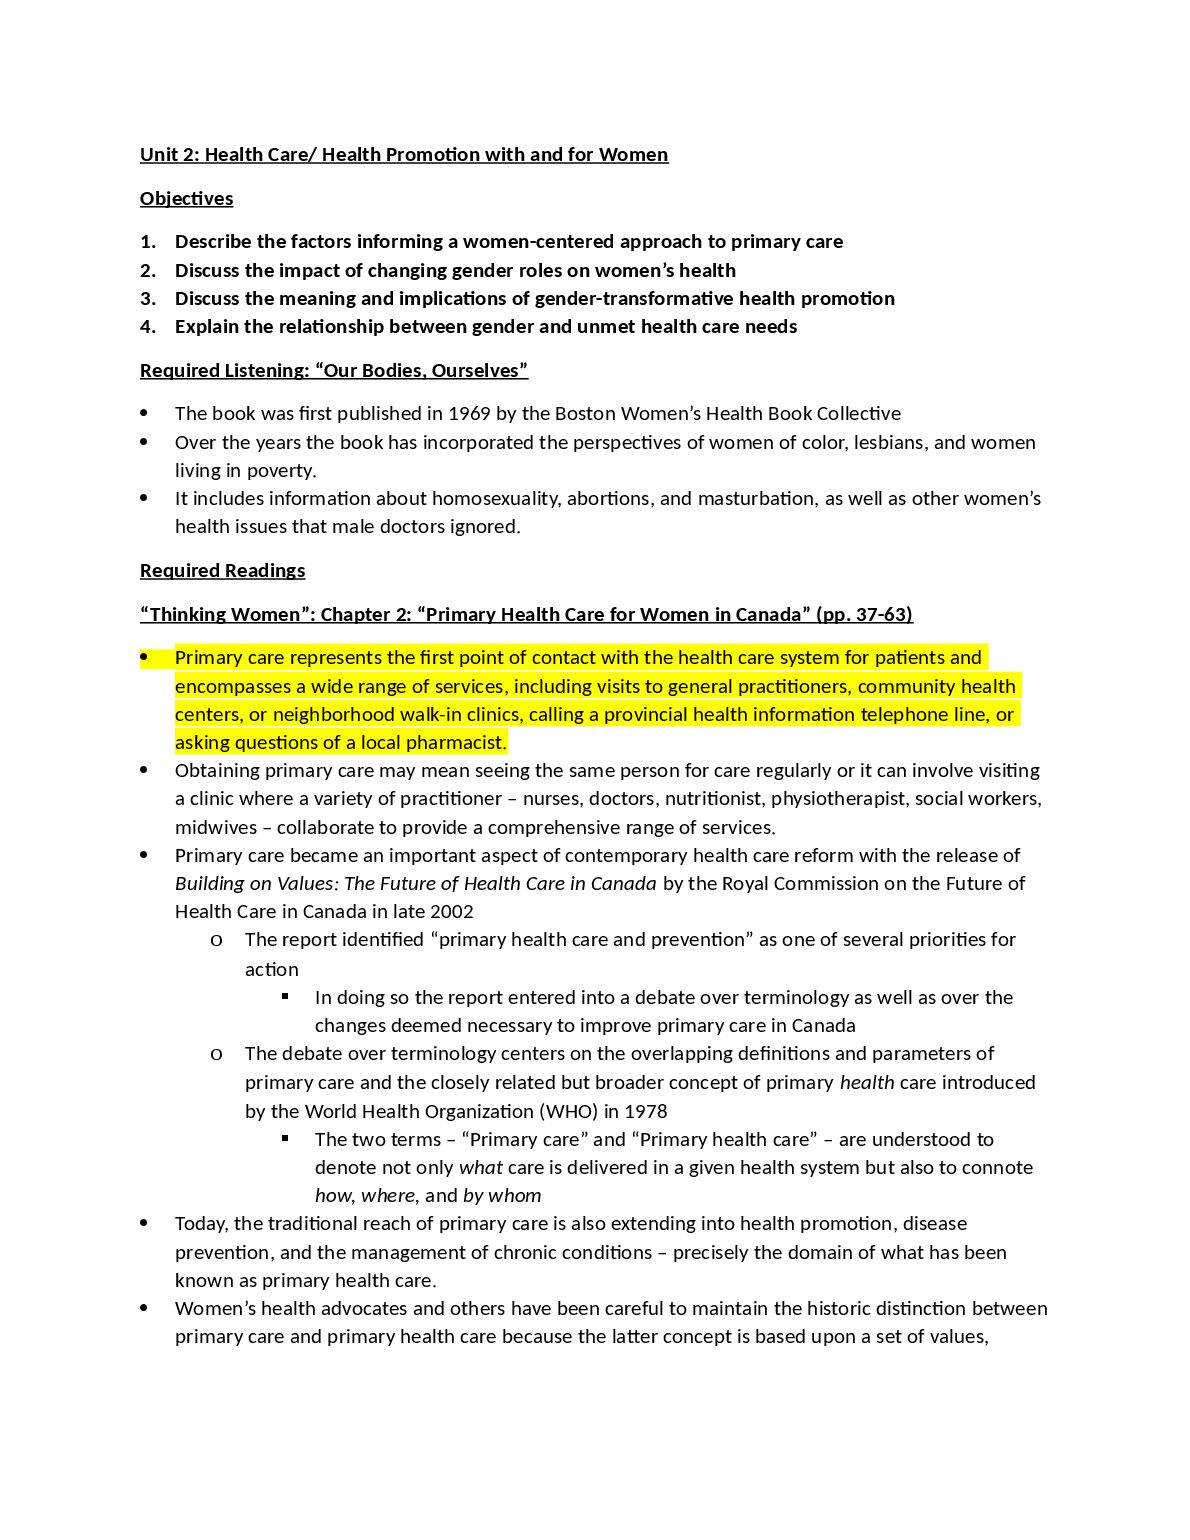
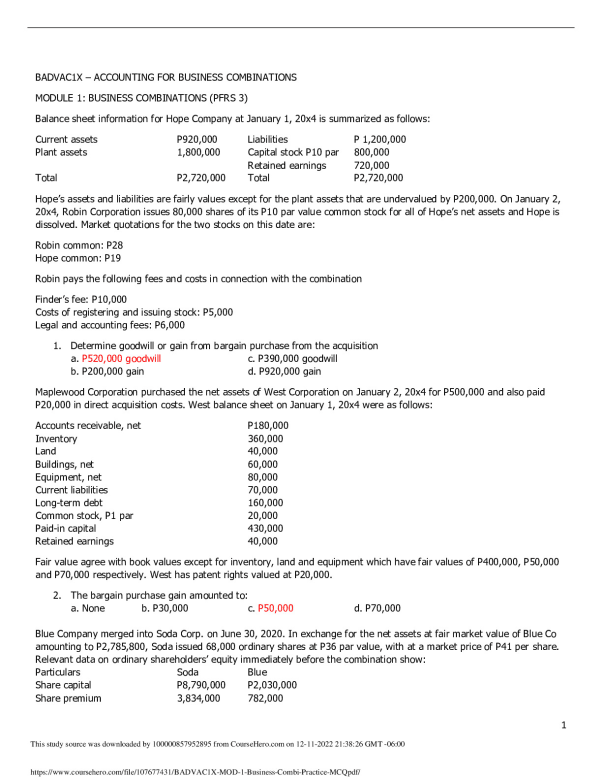
BADVAC1X – ACCOUNTING FOR BUSINESS COMBINATIONS MODULE 1: BUSINESS COMBINATIONS (PFRS 3) Balance sheet information for Hope Company at January 1, 20x4 is summarized as follows: Current assets P920,000 Liabilities P 1,200,000 Plant assets 1,800,000 Capital stock P10 par 800,000 Retained earnings 720,000 Total P2,720,000 Total P2,720,000 Hope’s assets and liabilities are fairly values except for the plant assets that are undervalued by P200,000. On January 2, 20x4, Robin Corporation issues 80,000 shares of its P10 par value common stock for all of Hope’s net assets and Hope is dissolved. Market quotations for the two stocks on this date are: Robin common: P28 Hope common: P19 Robin pays the following fees and costs in connection with the combination Finder’s fee: P10,000 Costs of registering and issuing stock: P5,000 Legal and accounting fees: P6,000 1. Determine goodwill or gain from bargain purchase from the acquisition a. P520,000 goodwill c. P390,000 goodwill b. P200,000 gain d. P920,000 gain Maplewood Corporation purchased the net assets of West Corporation on January 2, 20x4 for P500,000 and also paid P20,000 in direct acquisition costs. West balance sheet on January 1, 20x4 were as follows: Accounts receivable, net P180,000 Inventory 360,000 Land 40,000 Buildings, net 60,000 Equipment, net 80,000 Current liabilities 70,000 Long-term debt 160,000 Common stock, P1 par 20,000 Paid-in capital 430,000 Retained earnings 40,000 Fair value agree with book values except for inventory, land and equipment which have fair values of P400,000, P50,000 and P70,000 respectively. West has patent rights valued at P20,000. 2. The bargain purchase gain amounted to: a. None b. P30,000 c. P50,000 d. P70,000 Blue Company merged into Soda Corp. on June 30, 2020. In exchange for the net assets at fair market value of Blue Co amounting to P2,785,800, Soda issued 68,000 ordinary shares at P36 par value, with at a market price of P41 per share. Relevant data on ord
![MGT 301 Business Strategy Chapter_Review Study Sheet_ Comprehensive Study Guide & Solutions] preview image](https://browseimages.nyc3.digitaloceanspaces.com/unlock-images/2026/Oct/14/paper-104210-preview-1-NfnUEH.jpg)