STUDY GUIDE > Rauch AG leases Jakarta State Polytechnic ACCOUNTING 125
Related tags
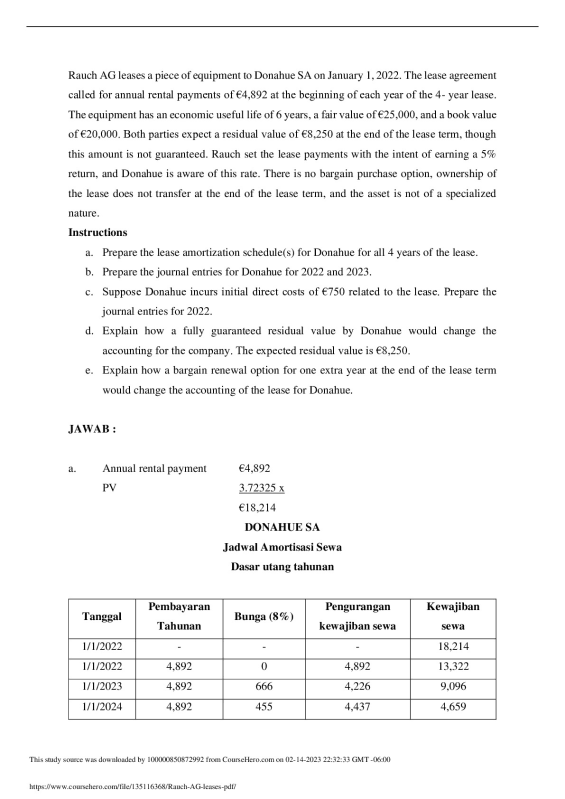
ACCOUNTING 125Jakarta State Polytechnic ACCOUNTING 125 Rauch AG leases a piece of equipment to Donahue SA on January 1, 2022. The lease agreement called for annual rental payments of €4,892 at the beginning of each year of the 4- year lease. The equipment has an economic useful life of 6 years, a fair value of €25,000, and a book value of €20,000. Both parties expect a residual value of � ...[Show More]
Access Full Document
Instant download
Preview 1 out of 2 pages
Reviews( 0 )
No Recommended Resources Yet.
| Category: | STUDY GUIDE |
| Number of pages: | 2 |
| Language: | English |
| Last updated: | 3 years ago |
| Downloads: | 1 |
| Views: | 26 |
![MGT 301 Business Strategy Chapter_Review Study Sheet_ Comprehensive Study Guide & Solutions] preview image](https://browseimages.nyc3.digitaloceanspaces.com/unlock-images/2026/Oct/14/paper-104210-preview-1-NfnUEH.jpg)